Modular Coordination: Why Industrialised Construction Stalls Without a Grid
Ask a precast plant manager what he wants from a design office. Sooner or later you get the same answer: tell me what you are going to order before you order it.
That sounds like a modest request. It rarely happens.
A factory pricing a residential scheme is usually quoting elements it has never made in those dimensions, will probably never make again, and cannot tool for until the design is frozen. Each of those conditions adds cost. None of them is technical problems. They are modular coordination problems, and they are older than anyone currently working in the industry.
The standards already exist. Nobody has a reason to use them
Modular coordination is neither new nor unresolved.
ISO 1006 specifies that the basic module, M, is 100 mm. ISO 2848 sets out the principles and rules and prefers multiples of 3M and 6M, 300 mm and 600 mm, because those numbers divide cleanly into most building dimensions. In the UK, BS 6750 pulled the ISO material into a single specification in 1986. BS ISO 21723 later replaced it.
So the document exists. It has existed for forty years. The barrier to dimensional coordination in Irish and British construction is not a lack of standards. Nobody in the supply chain has a commercial reason to follow one.
Compliance costs money in the year you adopt it. The return arrives later, spread across projects nobody has won yet, and it lands mostly with the manufacturer rather than with the designer who sets the dimensions. That is a poor incentive structure. It explains forty years of shelf life better than any argument about creativity or constraint.
What a national grid looks like when someone enforces it
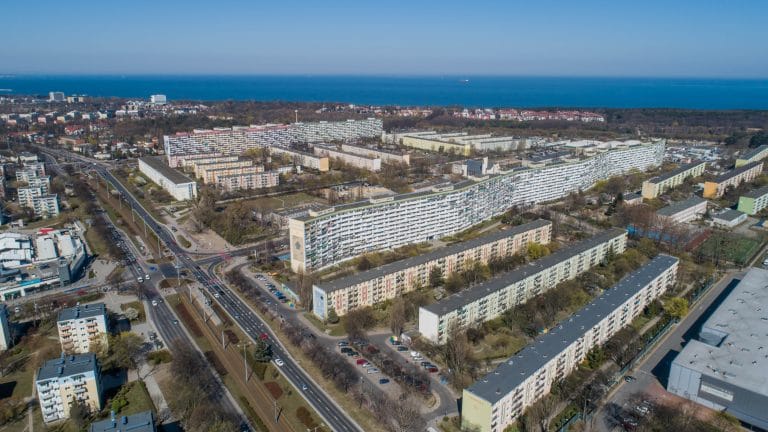
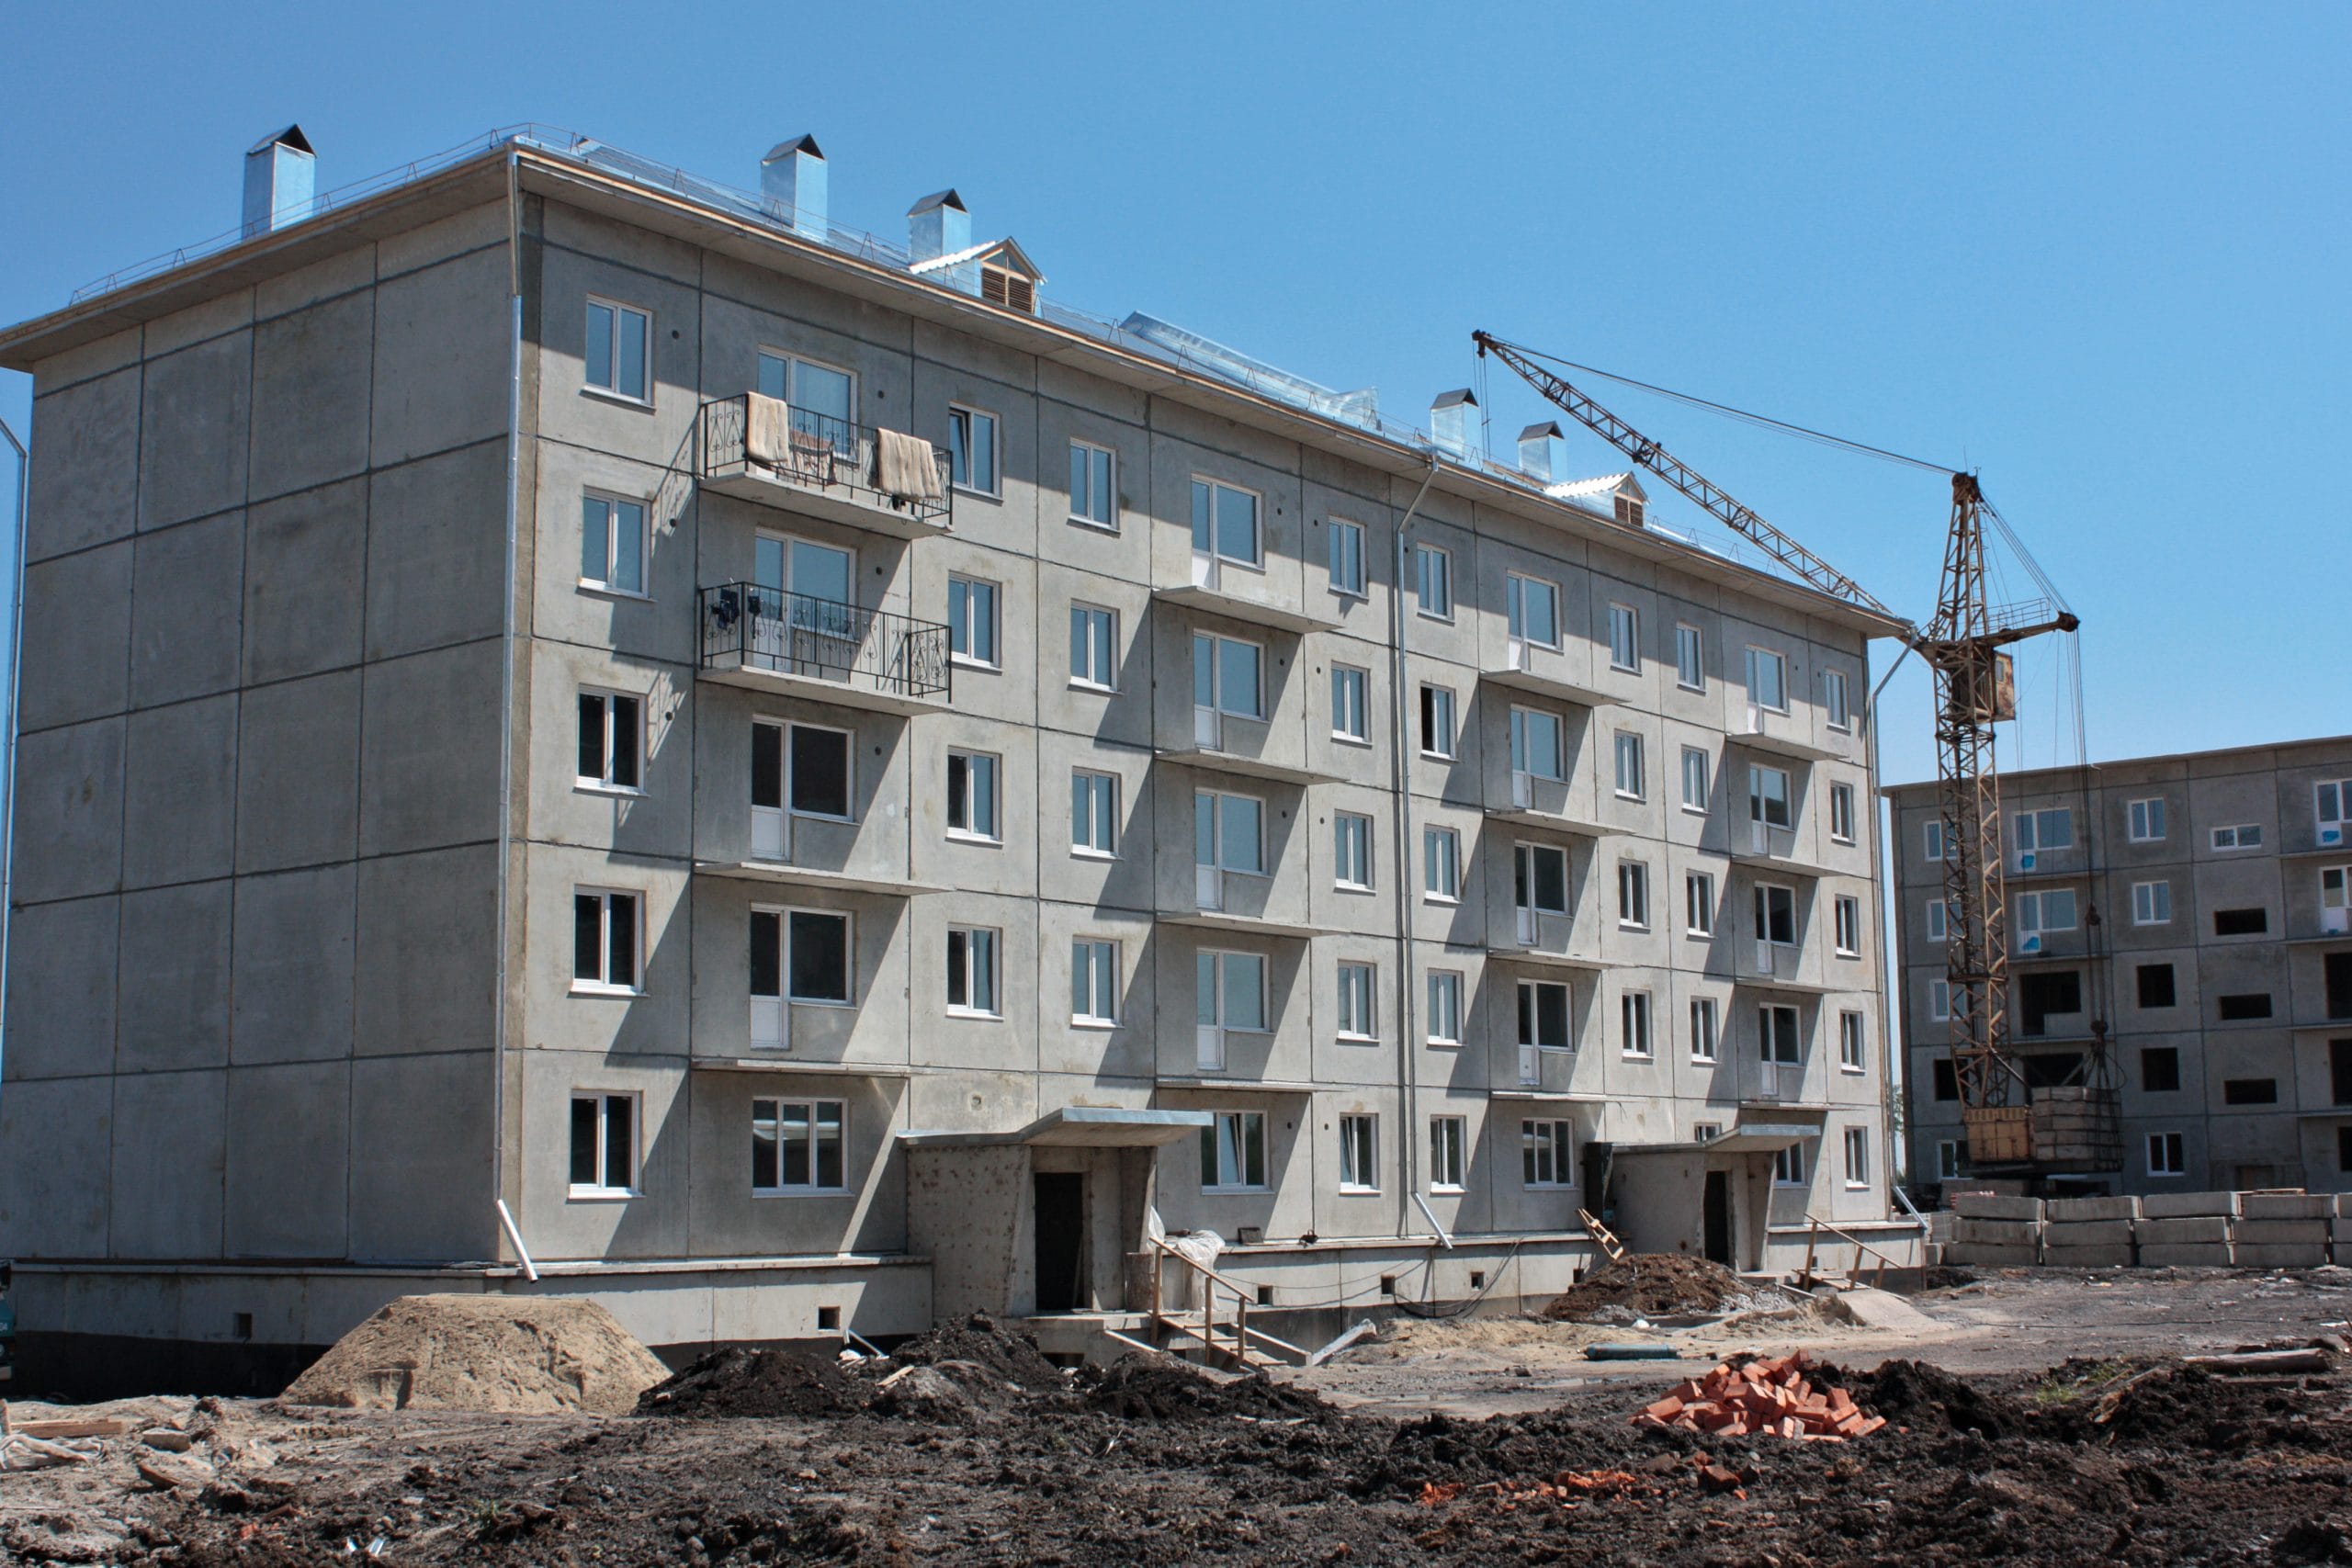
I recently wrote about Polish large-panel precast systems and what they still teach us about connection quality. The dimensional half of that story deserves separate treatment, because it maps directly onto DfMA today.
Polish coordination rules of the period set the basic module at 10 cm. The horizontal planning grid for residential and public buildings ran in multiples of 6M, meaning 60 cm, with main modular axes from 180 cm to 1200 cm in 60 cm steps and a standard residential storey height of 280 cm.
The Institute of Building Technology in Warsaw developed the W-70 system around 1970, and it sat directly on that grid. Load-bearing wall spacings were 240, 360, 480 and 600 cm. Internal wall panels were 15 cm thick and 253 cm high, and were available in lengths from 120 to 600 cm in 60 cm increments. Hollowcore floor units were 22 cm deep, with widths of 120, 180, and 240 cm, and lengths matching the wall spacings.
Read that list as a manufacturer rather than as an architect. It is not a design constraint. It is a product catalogue. A plant knew, before any particular project existed, which elements it would make for the next decade, in what quantities, on which beds, with what reinforcement and to what tolerances.
The catalogues were also more flexible than these estates’ reputation suggests. They organised components into three tiers: central typification for items made in plants nationwide, regional typification for local conditions, and local typification for a single estate. Variety sat inside the system rather than outside it. By 1980, Poland operated roughly 150 large precast plants, according to the national typology brochure NAPE prepared for the EU TABULA project.
What a modular grid buys the factory
The mould argument is real, but it is no longer the main one
The Precast/Prestressed Concrete Institute’s Mid-Atlantic chapter puts the case plainly: the largest single factor in precast manufacturing cost is repetition of the panel design, since every reuse of a form pulls the unit price down. That has not stopped being true.
the largest single factor in precast manufacturing cost is repetition of the panel design
It has stopped being the whole argument, though. Automated shuttering on a pallet circulation line repositions the magnetic side rails to match the geometry specified in the file. Changeover cost per element has fallen significantly since the 1970s. Geometric variation is cheaper than it used to be, and anyone selling a grid purely on formwork economics is describing a factory that no longer exists.
The bigger saving sits outside the mould.
Everything the mould does not cover still has to be worked out. Reinforcement cage design, plus the mesh and bar programmes if the plant is automated. Cast-in items: lifting anchors, sockets, connection details, service penetrations. Stacking and racking in the yard. Load configuration on the trailer. Rigging on site.
Each of those is an engineering decision. If dimensions repeat, the decision repeats at no cost. If they do not, somebody solves it again at full price, usually under programme pressure.
Stock item or bespoke order
Underneath it all sits a commercial question. Can you buy the component, or must you make it?
A coordinated element is a stock item with a lead time. An uncoordinated one is a bespoke order with a lead time, a minimum quantity, a tooling charge and a delivery risk attached. That difference in purchasing behaviour is a large part of what separates construction from manufacturing.
A modular grid is three numbers, not one.
This is where most grid arguments quietly fall over. A coordinating dimension on its own is decoration. A working grid specifies three things: the grid’s coordinating dimension, the element’s manufacturing dimension, and the joint between them.
The Polish catalogues made all three explicit. They deliberately set W-70 internal wall panels shorter than their modular length, with recessed edges, and standardised the shortening. One group of panels lost 10 cm, and another lost 1 cm, depending on how the wall met its neighbour. The joint was a catalogued quantity rather than something the erector worked out on the day.
Tolerance is the other half of the system.
On the tolerance side, the framework here is more complete than on the dimensional side.
EN 13670, adopted in Ireland as I.S. EN 13670 with a National Annex added in 2015, covers execution of concrete structures. Section 10 deals with geometrical tolerances. It separates production tolerances defined in the product standards, erection tolerances covering the assembly’s location, verticality, and horizontality, and construction tolerances as the combination of the two. It defines normal and special tolerance classes and draws its tolerance vocabulary from ISO 1803. The authors of BS 6750 wrote it with ISO 3443 on tolerances and fits in mind. The same people designed coordination and tolerance as one system.
Again, the failure is not the document. EN 13670 requires the execution specification to state which tolerance class applies, and on most schemes nobody makes that decision deliberately. An element made to millimetres then meets foundations, in-situ cores, and steelwork, working to something much coarser. Nobody owns the accumulated deviation, so it lands on the precast erector, at the point in the programme where absorbing it costs the most. Watch who gets asked to solve it on site. That tells you who is carrying a risk they were never priced to carry.
The part everyone forgets: openings
Polish systems dimensioned door openings to the same 60 cm module the structure sat on. Internal wall panels came in two variants, with and without an opening, and both sat in the same length series. Joinery could then be run to a small number of sizes across a national programme, rather than being measured and made to fit each hole.
Now look at what gets ordered in Ireland. Merchants stock two internal door families, but they don’t align.
The imperial family runs 1981 and 2032 mm high, in widths of 610, 711, 762, 813 and 864 mm. Those are 6’6″ and 6’8″ by 2’0″ to 2’10”, converted after the fact. The metric family runs 2040 mm high, in widths of 526, 626, 726, 826 and 926 mm. Anything scheduled outside both is treated as made-to-order. Not one of those dimensions is a multiple of 100 mm. The imperial family could never be, since it started in inches. The metric family is not either.
Two uncoordinated stock families plus a made-to-order tail put a manufacturer in a worse position than one badly chosen standard. With a single convention, however awkward, a producer can tool around it, fix the reinforcement detailing around a known opening and treat the panel as a catalogue item. With three possibilities, every opening becomes a fresh engineering decision for a wall panel that would otherwise be repeatable.
That is the real cost. Openings are where the structural element, the joinery supplier, the fire strategy and the accessibility requirement all meet. An uncoordinated opening means bespoke reinforcement around a bespoke void. At that point, the panel stops being a product and becomes a one-off.
Where the argument gets weaker
The case for grids gets oversold, so here are three limits worth stating.
A grid does not fix a housing shortage
Poland had the most disciplined dimensional standard in Europe and still failed to house its population. Output peaked at roughly 283,600 dwellings in 1978, the highest figure the country has ever recorded, then fell away as the economy deteriorated. By 1990, estimates put the gap between available dwellings and households needing them at between 1.6 and 1.8 million units.
What broke Polish output at the end of the 1970s was the economy, not the module. Anyone claiming a grid solves a housing shortage is claiming far more than the record supports.
The savings evidence is thinner than the marketing
McKinsey’s 2019 report on modular construction found a 20 to 50 per cent schedule acceleration and argued that leading players optimising for scale could achieve more than 20 per cent in construction cost savings. The same report stated plainly that cost savings were the exception, not the norm, at the time of writing.
The Forge in Southwark is the most cited project on the platform side. Bryden Wood publishes a 9.5 per cent capital cost reduction, a 13 per cent programme reduction and 40 per cent less steel. Cundall, independently verifying the figures on behalf of Landsec, reports a 39 per cent cut in upfront embodied carbon, measured against a business-as-usual design priced in 2018.
Read those numbers carefully before repeating them. They are good results for a first deployment of a new system. They are also a good deal more modest than the headline percentages that circulate in platform marketing, and that gap is the useful part. First deployments capture the least value because learning hasn’t happened yet. The return on a grid comes from the fifth building rather than the first, which is exactly why no single project can justify the investment.
Monotony is an objection to the catalogue, not the grid
This question decides the outcome, and it has no comfortable answer.
In Poland, a state institute provided the grid and imposed a single national system on a market with no alternatives. That route is neither available nor desirable here. A grid set by a single supplier is a competitive weapon, and competitors will refuse to adopt it. An industry-body grid with no procurement power gets published and then ignored, as happened to BS 6750.
That leaves the client side, and specifically the repeat client. Ireland has moved further here than most people notice. The Department of Housing applies the Design Manual for Quality Housing and the Employer’s Requirements for Detail Design of Quality Housing to social housing schemes, and has signalled an intention to require standardised designs where possible, alongside modern methods of construction. The 2025 apartment planning standards revised minimum floor areas, dual aspect ratios, floor-to-ceiling heights and core ratios.
Standard layouts and standard specifications are not the same thing as dimensional coordination for manufacture, though. The Design Manual covers site layout principles and the internal layouts of dwellings. That standardises the product. Coordinating the dimensions of the components that make up the product and the tolerances that allow those components to meet is a separate decision. As far as I can see, nobody has taken it.
The State is now the country’s largest repeat housing client. Its current housing plan targets 300,000 homes between 2025 and the end of 2030, against 36,284 completions recorded by the CSO for 2025. That is a client with enough forward volume to make a grid stick. It is the only actor in the market that has.
What this means for a precast plant
A modular grid does not make buildings cheaper on its own. It enables repeat manufacturing, which is a narrower and more honest claim. It turns a factory from a shed doing bespoke work into a plant with a product range. It also turns the procurement conversation from “quote me this” into “how many do you want”.
Standards for doing this were written decades ago, and the current versions still sit on the shelf, on both the dimensional and tolerance sides. The Polish programme showed, at a national scale, what happens when someone enforces one, including the parts that failed badly. Ireland and Britain have never had anyone with both the authority and the forward order book to set a grid and keep it.
Until that changes, offsite factories in these islands will keep tooling up for orders that arrive one at a time, in dimensions nobody agreed in advance. And we will keep wondering why the productivity gains never quite show up.
An AI model was used to research and redact the text.